You found mold spreading across the wall, the remediation quote is $4,000, and now you are wondering if your homeowners insurance will help pay for it. The honest answer is maybe, and the deciding factor is almost never the mold itself. It is what caused the mold in the first place.
Insurance companies treat mold as a consequence, not a cause. If the moisture that fed the mold came from a covered peril, like a burst pipe, the resulting mold remediation is often covered too. If the moisture came from something excluded, like long-term neglect or flooding, the mold claim goes down with it. This guide explains the fine print so you know where you stand before you file.
The short answer
Standard homeowners insurance typically covers mold remediation only when the mold resulted from a covered water loss. A pipe bursts, soaks the drywall, and mold grows in the damp cavity: the mold cleanup is usually part of the same claim. A roof leaks for two years because nobody maintained it, and mold takes over the attic: that is generally excluded as a maintenance issue.
Think of it as a chain. The insurer looks at the first link, the source of the moisture, and everything downstream follows that decision. This is why documenting the water event matters as much as documenting the mold. Our guide to what homeowners insurance covers for water damage explains which sources of water qualify as covered perils.
When mold remediation IS covered
The clearest covered scenario is mold that grows after a sudden, accidental water event. Common examples include:
- A supply line bursts under the sink and mold develops inside the cabinet and wall cavity
- A water heater ruptures and mold appears in the surrounding drywall within days
- An appliance hose fails during a wash cycle, soaking the laundry room floor
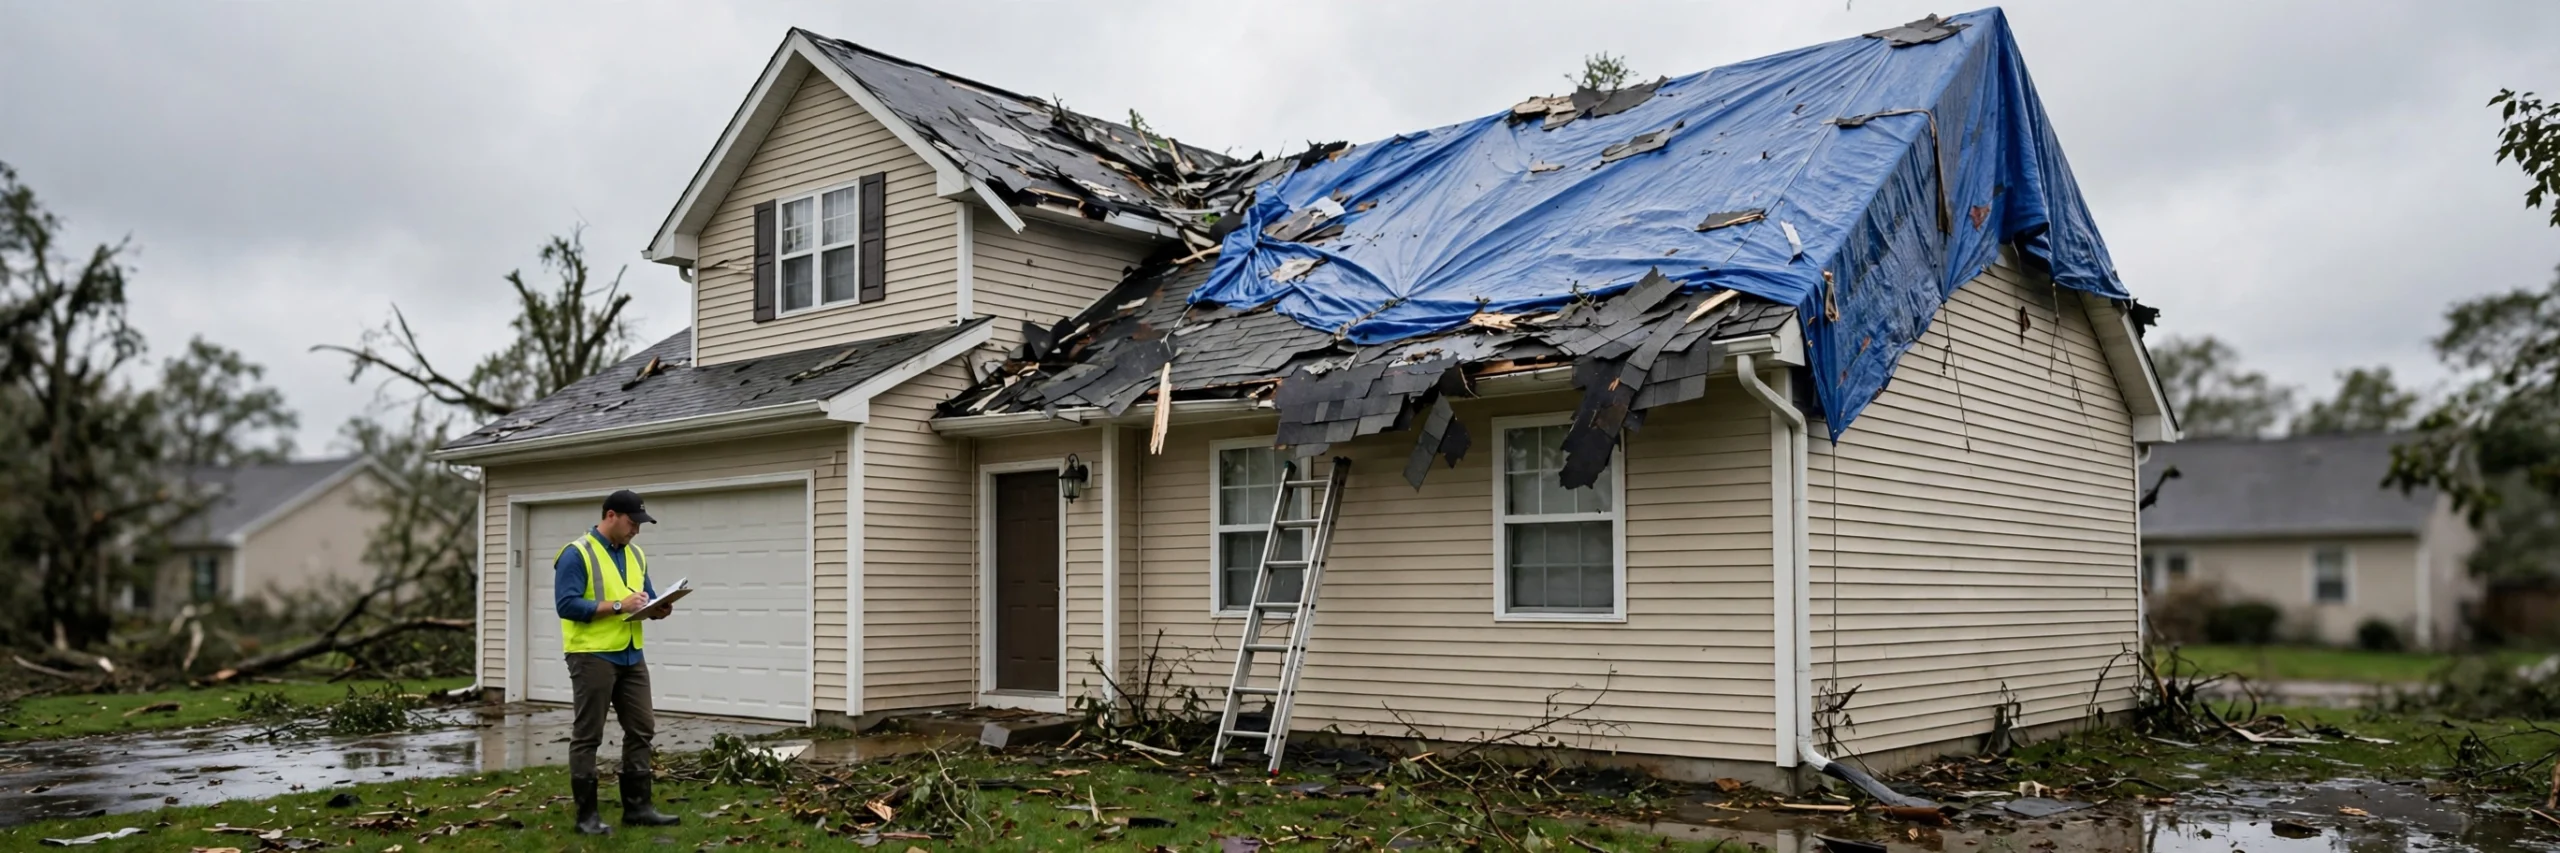
- Wind damages the roof in a storm, rain enters, and mold follows in the attic
In these cases, mold remediation is treated as part of repairing the covered loss. The insurer pays to fix the water damage and to remediate the mold that resulted from it. Burst pipe claims are the classic example, since the sudden failure and the resulting mold are tightly linked in time.
When mold remediation is NOT covered
The exclusions are where most mold claims die. Insurers routinely deny mold remediation when:
- The mold came from flooding, which is excluded under standard homeowners policies
- The moisture built up over months from a slow leak the homeowner did not address
- High indoor humidity caused condensation mold with no covered water event behind it
- The home was vacant or unoccupied beyond the policy’s vacancy limit
- A previous water loss was never properly dried, letting mold colonize the same area again
That last point catches people off guard. If you had a covered leak last year, dried the surface, but left moisture inside the wall, a second mold claim in the same spot can be denied as a pre-existing or unrepaired condition. Proper drying the first time is both a health measure and an insurance strategy.
Caps and sublimits: the number nobody reads
Even when mold is covered, most policies cap the payout with a mold sublimit. Typical caps run from $1,000 to $10,000, far below the policy’s overall dwelling limit. A $10,000 cap sounds reasonable until the remediation quote comes in at $12,000 and the drywall rebuild adds another $8,000.
Check your policy’s declarations page and endorsements for the words fungus, mold, or microbial. Some policies exclude mold entirely except for a small testing allowance. Others offer a mold buyback endorsement that raises the cap to $25,000 or $50,000 for an added premium. If you live in a humid climate or an older home with aging plumbing, that endorsement is worth pricing out. It is usually a fraction of one remediation bill.
Mold becomes a problem inside a home when there is excessive moisture, and the key to control is moisture control. That principle from federal guidance is also the insurer’s view: control the water event, and the mold question usually answers itself.
How to file a mold claim that gets paid
Filing follows the same playbook as any water damage claim, with a few mold-specific twists. First, report promptly. Mold spreads fast, and delays give the insurer room to argue the growth was preventable. Second, get the moisture source identified in writing by a plumber or restoration contractor, because the cause determines coverage.
Third, consider professional mold testing if the insurer questions whether mold is actually present or how far it spread. A few hundred dollars for an independent assessment can protect a multi-thousand-dollar claim. Fourth, do not start tearing out walls before the adjuster inspects, though you should continue emergency steps like stopping the water and running dehumidifiers. Our walkthrough of how to file a water damage claim covers documentation in detail.
Preventing the denial before it happens
The best mold claim is the one you never need, but the second best is the one your maintenance records support. Keep receipts for roof work, plumbing repairs, and HVAC service. Fix leaks the week you find them, not the season you get around to it. Run bathroom exhaust fans, keep indoor humidity under 60 percent, and check under sinks twice a year. If a claim ever comes, that paper trail proves you were a responsible homeowner, which is exactly what the policy requires.
If your claim is denied anyway, you have options. Our article on denied water damage claims lays out five moves, in order, from formal appeal to state regulator complaints. And if the damage came from a declared disaster, FEMA assistance programs may help with costs insurance will not touch. For general flood safety context, Ready.gov is a useful reference.
Note: This is general information, not legal or insurance advice. Coverage depends on your specific policy and state rules, so check with your insurer or agent.
Frequently Asked Questions
Does homeowners insurance cover black mold specifically?
Insurers do not usually distinguish between mold types. The same rule applies: black mold from a covered water loss is typically covered up to the mold sublimit, while black mold from neglect, flooding, or long-term leaks is not. The color of the mold matters far less than the source of the moisture.
What is a typical mold coverage cap?
Most standard policies include a mold, fungus, or microbial sublimit between $1,000 and $10,000. Some policies exclude mold almost entirely. Check your declarations page for the exact figure, and ask your agent about a buyback endorsement if the cap looks low for your home’s risk.
Will insurance pay for mold testing?
Sometimes. If testing is needed to scope a covered claim, insurers often pay for it as part of the loss. If you order testing on your own before filing, you may pay out of pocket, though the results can strengthen your claim. Ask your adjuster before scheduling independent testing.
Can I file a mold claim without a water damage claim?
You can, but it is an uphill climb. Mold without an identifiable covered water event is usually attributed to humidity, condensation, or maintenance, all of which are excluded. If you suspect a hidden leak is the cause, get a plumber or restoration contractor to confirm it in writing first.
Does flood insurance cover mold after a flood?
NFIP flood insurance can cover mold remediation that results from a covered flood, but with the program’s usual limits and basement restrictions. Document the flood damage thoroughly, since the EPA notes that mold can begin growing within 24 to 48 hours of flooding.
What to do next
Mold coverage comes down to one question: what got the wall wet? If the answer is a sudden, covered water event, file promptly, document the cause, and expect the mold remediation to ride along with the water claim, subject to your policy’s cap. If the answer is murky, get a professional to pin down the cause in writing before you call the insurer. Either way, start with our guide to how to file a water damage insurance claim so the paperwork supports you from the first phone call.