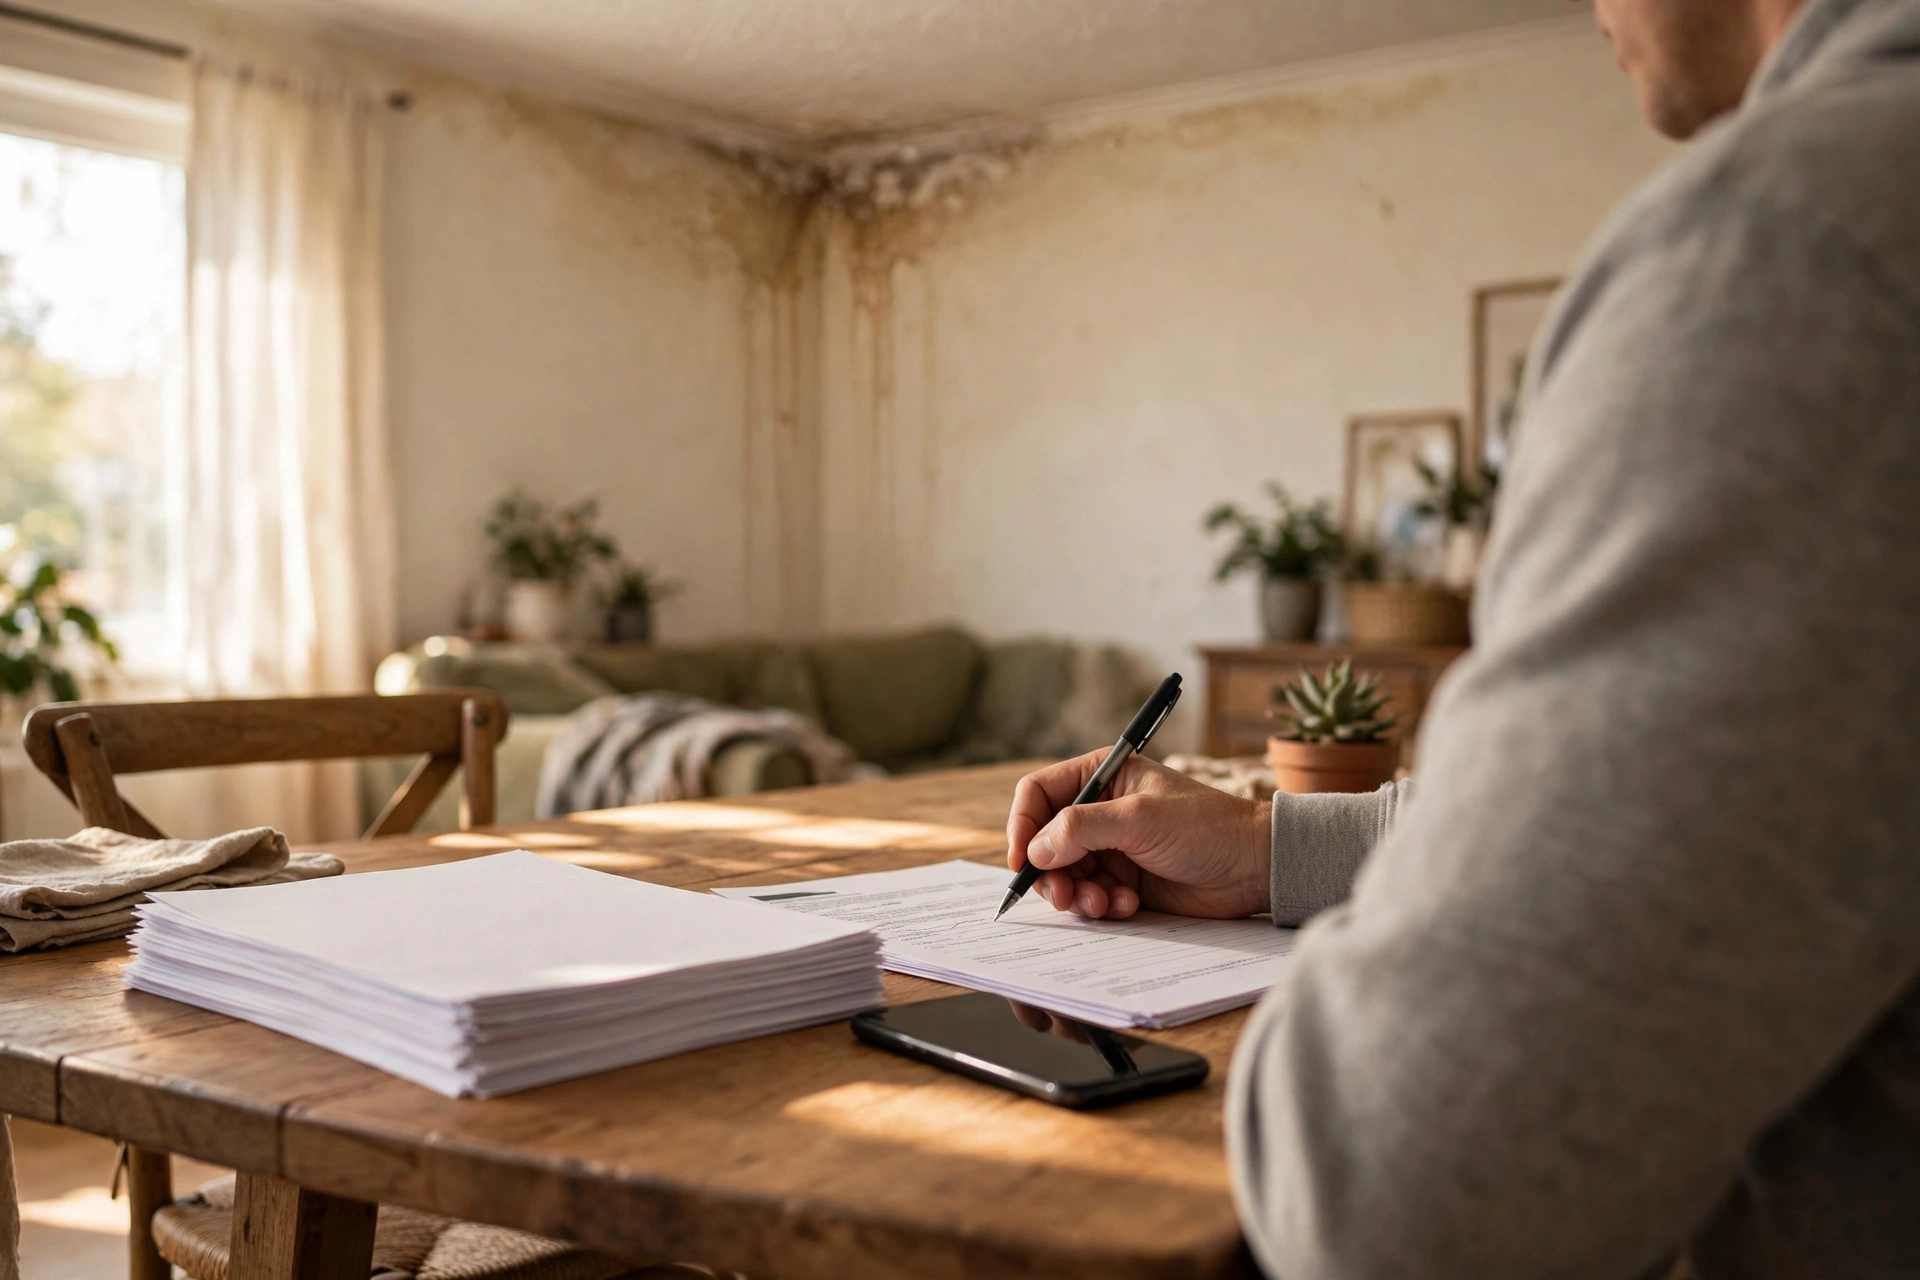
You just found water damage in your home, and between the wet drywall and the musty smell, one question keeps nagging you: how long do I actually have to file a claim? It is a fair question, because the answer is not one number. Your policy sets one deadline, your state sets another, and missing either one can cost you the entire payout.
This guide breaks down both deadlines in plain language. You will learn what “prompt notice” really means, how long you have to sue if your insurer denies or underpays you, and what the rules look like in major states. None of this replaces your actual policy language, so pull that document out while you read.
Why timing matters more than most homeowners think
Insurance companies deny water damage claims for late reporting more often than people expect. The policy you signed almost certainly includes a “duties after loss” section, and one of those duties is notifying the insurer promptly. Wait too long and the adjuster has a ready-made reason to question everything: Was the damage really sudden? Did it get worse because you sat on it? Could they even investigate properly months later?
Late filing also hurts you in practical ways. Water damage gets worse with time. A small leak that would have cost a few thousand to fix can turn into a five-figure mold remediation job within weeks. And if you need to protect your home from further damage (which your policy requires you to do), every day of delay adds out-of-pocket cost. Filing early is not just about the rules; it is about keeping the damage, and the bill, as small as possible.
The two deadlines you need to know about
There are really two separate clocks running, and people mix them up all the time.
Deadline 1: Notice to your insurer
This is the “prompt notice” requirement. Most homeowners policies say you must notify the company “as soon as practicable” or “promptly” after a loss. Some policies name a specific window, often 24 to 72 hours for water losses. This clock starts when you discover the damage (or reasonably should have discovered it), not when the leak started.
Deadline 2: Filing suit if the claim goes wrong
If your insurer denies your claim, lowballs the settlement, or drags its feet, you have a limited time to file a lawsuit. This deadline comes from two places: a “suit against us” clause in your policy (often one to two years) and your state’s statute of limitations for breach of contract. The shorter of the applicable limits is the one that matters.
Think of it this way: the notice deadline gets your claim in the door, and the suit deadline is your backstop if the insurer does not treat you fairly. You need to respect both. Our step-by-step claim filing guide walks through the notice process in detail.
What “prompt notice” looks like in practice
No state defines “prompt” as an exact number of hours across the board, but here is how it plays out in the real world:
- Sudden, obvious damage (burst pipe, appliance flood): most adjusters expect notice within 24 to 72 hours of discovery. Same-day or next-day is ideal.
- Hidden damage found later (leak inside a wall, slow seep): the clock generally starts when you discover it. Document when and how you found it.
- Storm or flood damage: insurers expect high claim volumes after big events, but you should still report within days, not weeks. Ready.gov’s flood guidance stresses documenting everything from the start.
When in doubt, report early and in writing. A phone call gets things moving, but follow it with an email or portal message so you have a timestamp. Keep a simple log: date you found the damage, date you called, who you spoke with, and your claim number.
Deadlines by state: suit limitation examples
The time limit for suing your insurer over a denied or underpaid claim varies by state. These are common examples, not legal advice, and your own policy may impose a shorter contractual deadline:
- Texas: 2 years for breach of contract suits against insurers.
- California: many standard policies include a 1-year suit limitation; state contract law allows longer, but the policy clause usually controls.
- Florida: up to 5 years for written contracts, though policy language may shorten this.
- New York: the standard fire policy form sets a 2-year suit limitation.
- Illinois: typically 1 year under the standard policy suit clause.
Notice the pattern: the policy’s own “suit against us” clause is often the binding limit, and it is frequently just one year from the date of loss. That is much shorter than most people assume. Also note that federal flood insurance (NFIP) plays by its own rules: you generally must submit proof of loss within 60 days and file suit within one year of a written denial. FEMA’s site has the current NFIP claims handbook if you carry flood coverage.
One more wrinkle: some states pause (“toll”) the clock while the insurer is still handling your claim, and some do not. Do not assume you have extra time. If a denial or an unreasonably low offer arrives, talk to a licensed public adjuster or attorney promptly rather than hoping the deadline stretches.
What happens if you miss a deadline
Missing the notice deadline does not automatically kill your claim in every state. Many states require the insurer to show it was actually harmed (“prejudiced”) by the delay before it can deny on those grounds. But “not automatic” is not the same as “fine.” A late-notice fight adds months to your claim and gives the insurer leverage to reduce the payout.
Missing the suit deadline is far more serious. Once the statute of limitations or the policy’s suit clause expires, courts will almost always throw out your case, no matter how valid the underlying claim was. That is why the suit deadline deserves a calendar reminder the day you file your claim, especially if the insurer is slow-walking you.
Exceptions that can extend the clock
A few situations can pause or extend deadlines, though none are guaranteed:
- Hidden damage: if a leak was concealed inside a wall or under flooring, most states start the clock at discovery, not at the moment water first escaped.
- Ongoing handling: in some states, the suit clock pauses while the insurer actively investigates or negotiates.
- Minor policyholders: special rules can apply when the homeowner is a minor or legally incapacitated.
- Insurer misconduct: if the company misled you about deadlines, courts may extend them.
Treat every one of these as a maybe, not a plan. The safe move is always to act as if the shortest deadline applies.
What to do right now if you just found damage
- Stop the water source if you safely can (shutoff valve, water main).
- Take photos and video of everything before you move or clean anything.
- Call your insurer today, then follow up in writing with a timestamp.
- Mitigate further damage: move valuables, start drying. Your policy requires this, and it also fights mold. See our guide on preventing mold after water damage.
- Confirm what your policy covers while you wait. Our water damage coverage guide explains sudden versus gradual damage, and if sewage is involved, read about sewer backup endorsements since standard policies usually exclude it.
- Put the suit deadline on your calendar now, based on your policy’s “suit against us” clause.
Note: This is general information, not legal or insurance advice. Coverage depends on your specific policy and state rules, so check with your insurer or agent.
Frequently Asked Questions
How long after water damage can I file a claim?
Report it as soon as you discover it, ideally within 24 to 72 hours. Most policies require “prompt” notice, and some name a specific window. The separate deadline for suing over a denied claim is usually one to two years depending on your policy and state.
Can I file a claim for old water damage I just discovered?
Often yes, if the damage was hidden and you genuinely just found it. The notice clock typically starts at discovery. Document when and how you found it, and report it immediately. Gradual damage that was visible for months is much harder to claim.
Does filing late automatically deny my claim?
Not automatically in most states; the insurer usually must show the delay harmed its investigation. But late filing weakens your position and can reduce your payout, so it is never worth the risk.
What is the deadline for a FEMA flood insurance claim?
NFIP policyholders generally must submit a signed proof of loss within 60 days of the flood and have one year from a written denial to file suit. Check FEMA’s current guidance, since extensions are sometimes issued after major disasters.
Should I wait for all the damage to show before filing?
No. File as soon as you discover the loss, then supplement the claim as more damage becomes visible. Waiting lets mold grow and gives the insurer a late-notice argument.
Bottom line
Report water damage within days of discovering it, keep everything in writing, and calendar your policy’s suit deadline the same week you file. Deadlines are one of the few parts of a claim entirely within your control, so do not give the insurer a free reason to say no. If your claim has already been denied or stalled, review your options for filing and appealing the right way before the clock runs out.