Water is pouring through your ceiling or pooling across the basement floor, and once the immediate panic passes, a practical question takes over: how do I get my insurance to pay for this? Filing a water damage claim is not complicated, but the order of operations matters. Small mistakes early on, like throwing away damaged items before documenting them, can cost you thousands at settlement time.
This guide walks through the entire process in order: what to do before you call, how to document the damage, how to handle the adjuster, and how to evaluate the settlement offer. Follow these steps and you will avoid the most common claim-killing errors.
Before you file: understand what your policy likely covers
Not all water damage is covered. Standard homeowners policies typically cover sudden and accidental water damage: a burst pipe, an appliance hose failure, or rain entering through a storm-damaged roof. They generally do not cover flooding from outside the home (that requires separate flood insurance), long-term leaks you neglected, or sewer backup unless you purchased an endorsement.
This distinction decides whether filing makes sense at all. If the damage came from rising groundwater or a storm surge and you have no flood policy, a homeowners claim will likely be denied. Our guide on what homeowners insurance covers breaks down the common scenarios, and flood insurance vs homeowners insurance explains the gap that catches so many people off guard.
Also check your deductible before filing. If the damage is $1,200 and your deductible is $1,000, filing a claim for a $200 net payout may not be worth the claim on your record. Multiple claims can raise premiums or affect renewability.
Step 1: Stop the damage and document everything
Your policy requires you to mitigate further damage. Shut off the water main for plumbing failures, tarp a roof leak, and move undamaged belongings away from the water. Keep receipts for any emergency expenses like tarps, fans, or a plumber’s emergency visit; these are often reimbursable.
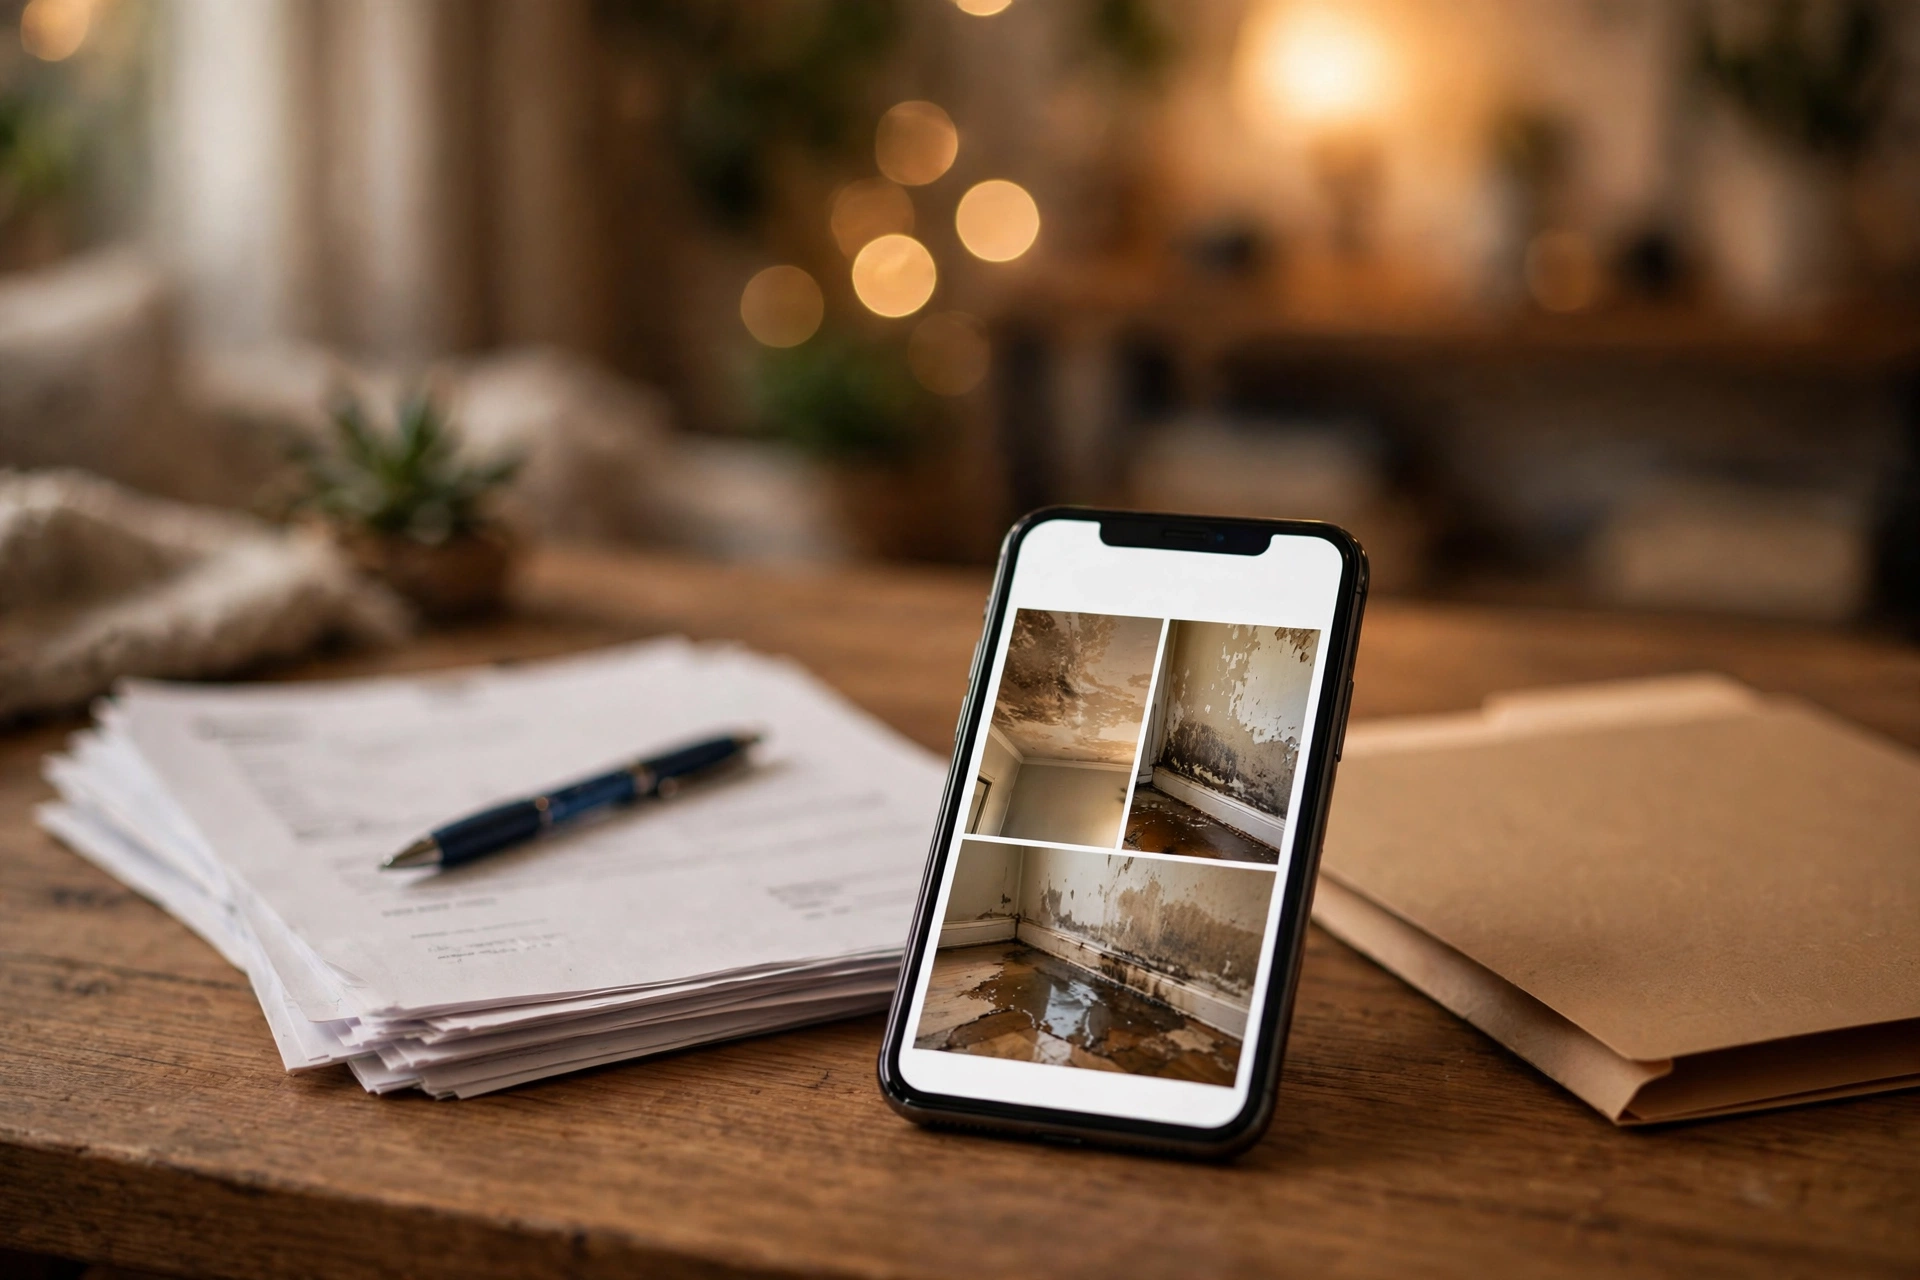
Then document before you clean. This is the step people rush, and it is the most important one:
- Photograph and video every affected room, including wide shots and close-ups of damage
- Capture the water source if visible (the burst pipe, the leaking appliance)
- Photograph damaged belongings where they are before moving them
- Save a sample of damaged materials if advised (carpet squares, for example)
- Write down the date, time, and how you discovered the damage
- Keep a running log of every call, with names, dates, and what was said
Do not throw anything away until the adjuster has seen it or your insurer gives written permission. Insurers can deny portions of a claim for items they never got to inspect. If you must discard something unsanitary, photograph it thoroughly first from multiple angles.
Step 2: Call your insurer promptly
Report the claim as soon as practical. Most policies require “prompt” notification, and delays give insurers room to argue the damage worsened due to neglect. Have your policy number ready and stick to facts: what happened, when, and what damage you can see.
During this call, ask specifically:
- What is my claim number?
- Is this type of water damage covered under my policy?
- What is my deductible?
- Do I have additional living expenses (ALE) coverage if I cannot stay in the home?
- Should I arrange emergency repairs, and what documentation do you need?
- When will an adjuster contact me?
Write down the answers. If coverage is confirmed verbally, note who said it and when. For a deeper dive on strategy, our water damage claim tips cover how to position your claim from day one.
Step 3: Meet the adjuster prepared
The adjuster inspects the damage and estimates the payout. This meeting heavily influences your settlement, so treat it seriously. Be present, be organized, and be factual.
Prepare a packet: your photo and video documentation, the inventory of damaged items with approximate ages and values, receipts for emergency expenses, and any contractor estimates you have already obtained. Walk the adjuster through the damage room by room. Point out everything, including damage that is easy to miss: baseboards, subflooring, insulation inside walls.
Answer questions honestly but do not speculate. If the adjuster asks how long the leak ran and you do not know, say so. Guessing “it must have been weeks” can trigger a neglect exclusion. Stick to what you observed.
Ask the adjuster to explain anything you do not understand, and take notes. If they mention exclusions or limitations, ask them to point to the specific policy language. You have every right to understand the basis of their decisions.
Step 4: Get your own repair estimates
Do not rely solely on the insurer’s estimate. Get two or three written estimates from licensed restoration contractors. Insurer estimates sometimes use standardized pricing software that undervalues local labor rates or misses scope items like mold remediation behind walls.
Compare line by line. Common gaps include:
- Missing mold remediation where water sat for more than 48 hours
- Underestimated drying equipment time
- Cosmetic-only repairs where structural drying is needed
- Omitted code upgrades required by local regulations
If your contractor’s estimate is higher, submit it with a polite written explanation of the differences. This is a normal part of negotiation, not a confrontation. Where mold is involved, remediation costs add up fast; our guide to professional mold treatments explains what proper remediation involves and why it costs what it does.
Step 5: Review the settlement offer carefully
The initial offer is exactly that: initial. Review the adjuster’s report line by line against your documentation and contractor estimates. Check that every damaged area and item appears, that depreciation calculations look reasonable, and that the deductible was applied correctly.
Understand the two payment structures. Actual cash value (ACV) pays the depreciated value upfront. Replacement cost value (RCV) pays ACV first, then reimburses the difference once you complete repairs and submit receipts (this is called recoverable depreciation). If you have RCV coverage, do not mistake the first check for the total payout.
If the offer is too low, respond in writing: itemize the discrepancies, attach your contractor estimates and photos, and request a reinspection or a specific explanation for each denied item. Keep every communication in writing from this point forward.
Common mistakes that hurt water damage claims
- Waiting too long to report: delays invite disputes about whether the damage worsened through neglect.
- Cleaning up before documenting. Once items are gone, proving their condition becomes your word against the insurer’s.
- Throwing away damaged property. Insurers can deny what they never inspected.
- Admitting fault or speculating. “I knew that pipe looked old” is a gift to the adjuster. State facts only.
- Accepting the first offer without review. Initial estimates frequently miss scope. Always compare.
- Not reading the policy. Endorsements, exclusions, and sub-limits (mold coverage is often capped) are in the fine print.
What to do if your claim is denied
A denial is not the end. Request the denial in writing with the specific policy language cited. Review it against your actual policy; adjusters sometimes apply exclusions incorrectly. You can appeal internally, request a reinspection, hire a public adjuster (who works for you, typically for a percentage of the settlement), or file a complaint with your state’s department of insurance.
FEMA assistance may also be available after federally declared disasters, even for uninsured losses. (Source: FEMA disaster assistance) And if flooding was involved, review flood safety and recovery resources at ready.gov while you sort out the financial side.
Note: This is general information, not legal or insurance advice. Coverage depends on your specific policy and state rules, so check with your insurer or agent.
Frequently Asked Questions
How long do I have to file a water damage claim?
Policies require “prompt” notice, which generally means days, not weeks. Some states set specific deadlines, and waiting too long can void coverage. Report as soon as you discover the damage, even before you know the full extent.
Will filing a water damage claim raise my rates?
It can. A single claim may or may not affect your premium, but multiple claims within a few years often trigger increases or non-renewal. Weigh the net payout against your deductible and claim history before filing small claims.
Should I start repairs before the adjuster visits?
Do emergency mitigation (stop the water, prevent further damage) but hold off on permanent repairs until the adjuster inspects. Document everything first. Insurers expect you to prevent further damage but want to see the original damage themselves.
What if the adjuster’s estimate is lower than my contractor’s?
Submit your contractor’s written estimate with a line-by-line comparison and request a reinspection. This negotiation is normal. If the gap persists, you can invoke the appraisal clause in most policies, which brings in a neutral umpire.
Does insurance cover mold caused by water damage?
Often yes, if the mold resulted from a covered water event, but many policies cap mold remediation at $1,000 to $10,000 unless you bought additional coverage. Check your policy’s mold sub-limit before assuming the full remediation cost is covered.
Bottom line
Filing a water damage claim is a process, not a phone call: document everything before cleaning, report promptly, meet the adjuster prepared with your own evidence, get independent estimates, and review the offer line by line before accepting. Most claim problems trace back to rushed documentation or unquestioned first offers. For tactics on strengthening your position throughout, read our water damage insurance claim tips next.